Secure Your Business With Corporate Life Insurance Solutions
Corporate-life-insurance.com.au is a broker-matching platform that helps Australian employers explore and compare corporate life insurance, group life cover and key person protection options from participating corporate insurance brokers in our nation-wide referral network. Explore clear explanations, market insights and tailored options designed to support employee wellbeing, reduce business risk and align life insurance benefits with your organisation’s budget and people strategy.
|
|
Life insurance quotes are provided by a selected broker from our referral network and may not represent all providers in the market. We may receive a referral fee at no cost to you. We do not provide financial advice or credit assistance directly.
Corporate life insurance for Australian employers
Corporate life insurance can support employees and safeguard your organisation if a team member dies, or becomes critically ill where the relevant cover is included. The right structure can combine group life insurance, key person cover and company paid life insurance to help manage financial risk and strengthen your employee value proposition.
Use this site to understand how corporate life insurance works in Australia, compare policy structures and learn how other organisations use life insurance for employees. You can also explore detailed guides in our articles library and stay updated via our latest news and insights.
Frequently Asked Questions
Customer Feedback
★★★★★
"The broker was fantastic and very helpful. He made the whole process very simple and explained everything in detail with very good suggestions. Will recommend him and look forward to future dealings with him. Thank You"
These are genuine reviews from customers who have used our broker referral service.
We work with licensed finance and insurance professionals across Australia and continually monitor the quality of our network, however individual experiences and outcomes may vary
Why consider corporate life insurance?
Protect your people: Provide life insurance for employees so their families receive financial support if the unexpected happens.
Manage business risk: Use key person life insurance to help your organisation recover from the loss of critical staff.
Support attraction and retention: Offer employee life insurance benefits as part of a competitive total rewards package.
Align cover with budget: Structure corporate term life insurance to balance premium costs with meaningful protection.
This week: a claims review finds insurers communication gaps on longer TPD and income protection cases, prompting fixes; ASIC begins another audit of adviser qualifications and warns licensees to keep the register accurate; life-insurtech LifeBid shifts to commercial rollout with major insurer integrations to speed policy servicing; and the Financial Services Minister backs a cautious path to price transparency, noting lessons from life insurances genetic testing limits. Takeaways for HR and CFOs: reinforce claims service expectations with insurers, verify your advisers status, ask providers about digital servicing and data security, and document risk‑reduction efforts to explain benefits costs clearly to staff.
Different businesses need different combinations of group life, voluntary cover and key person protection.
Explore how group life insurance cover works compared with individual policies, including eligibility, waiting periods and benefit levels. Understand when business life insurance for owners and directors is appropriate, and how premiums may be treated for tax purposes in Australia.
Our partner licensed corporate insurance brokers can review your current arrangements, explain options in plain language and help you compare quotes from multiple insurers in the market. Comparisons are based on insurers and products they can access and may not cover every provider. We do not assess your needs or provide advice; any guidance or recommendations will come from the broker. Use our tools on the calculators page to model scenarios before you decide.
Clarify the main components of a corporate life insurance program before you design or review your plan.
Group life insurance that provides a lump sum on death, often based on salary multiples or a fixed amount.
Optional total and permanent disability (TPD) and income protection benefits for broader employee cover.
Key person life insurance to help protect revenue, debt obligations and succession plans.
Learn how premiums are typically funded, how policies interact with superannuation and what to consider under Australian corporate life insurance regulations. You can find deeper explanations in our guides and FAQs.
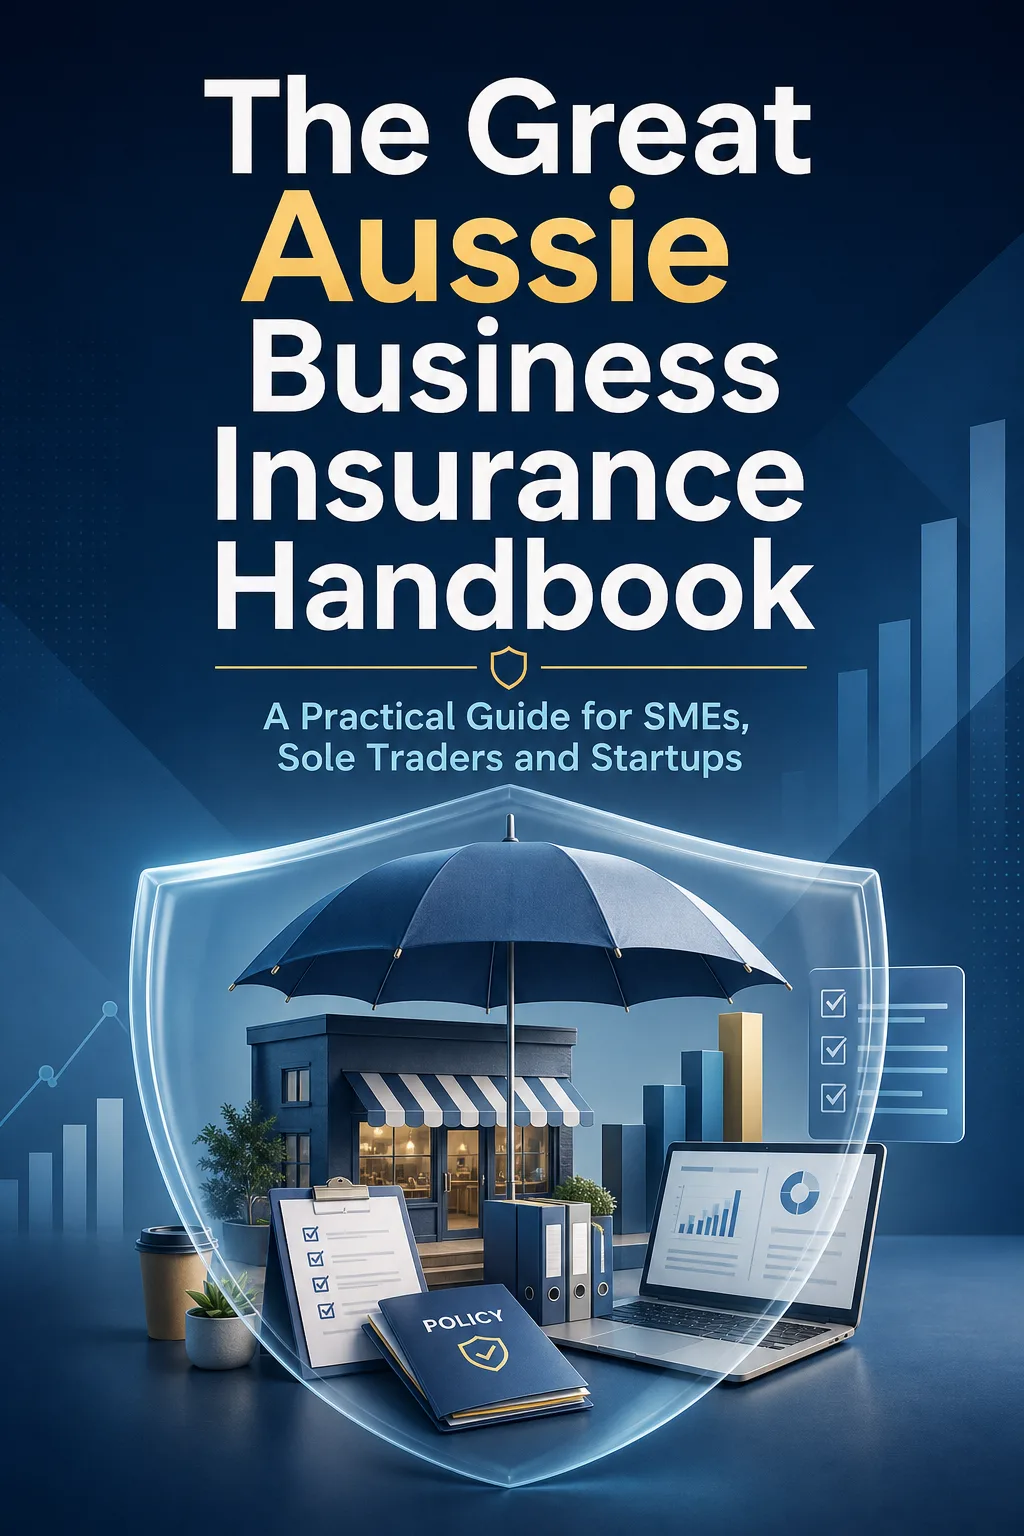
The Great Aussie Business Insurance Handbook: A Practical Guide for SMEs, Sole Traders and Startups
Business insurance can feel complex, but the risks facing Australian SMEs, sole traders and startups are very real. This plain-English guide explains how insurance fits into practical risk management, from public liability and professional indemnity to property, interruption, cyber and other common covers.
Inside, readers will learn how to assess their risk profile, understand common policy terms, compare business insurance quotes beyond price, and spot limits, exclusions and mistakes that can lead to gaps in cover. With checklists, FAQs and industry examples, it helps business owners approach insurance decisions with more confidence.
Submit an enquiry for referral to a participating broker to discuss your workforce, payroll, locations and existing insurance or superannuation arrangements.
Review any information and recommendations provided by the licensed broker outlining levels of cover, pricing, insurer options and policy structures.
Implement the chosen solution, onboard employees and set up ongoing reporting with broker support where available.
Corporate life insurance can play a role in your broader people, risk and financial strategies. Whether you manage HR, finance or operations, it helps to see how life insurance for employees fits with superannuation, salaries and other benefits.
Using life insurance as an employee benefit
Enhance your employee value proposition: Company paid life insurance can complement salary, leave and wellbeing programs.
Offer scalable benefits: Provide a base level of group cover, with staff able to top up at their own cost.
Support wellbeing initiatives: Many insurers offer add-ons such as wellness content, counselling and return-to-work support.
Stay informed about corporate life insurance trends, regulatory changes and market developments.
Use interactive tools on our insurance calculators page to estimate potential cover levels and costs.
Read in-depth articles and buyer’s guides covering corporate vs individual life insurance and policy design tips.
Follow sector updates and case studies in our news section to see how other Australian businesses respond to change.
For a more detailed discussion of your organisation’s needs, you can request support from licensed corporate insurance brokers in our referral network through our quote request form. We do not provide advice ourselves; any recommendations will be provided by the broker.
Australia’s life insurers have moved from broad reform talk to the harder task of deciding how mental health should be treated in future life insurance products, after the Council of Australian Life Insurers released its response to the independent Life Insurance Code of Practice review. For employers, the development matters because mental health claims, disability definitions, affordability pressures and staff communication all intersect in workplace insurance arrangements. - read more
The Life Code Compliance Committee’s 2025–26 Annual Report has put claims handling, benefit payment timeliness, customer communication and consent processes back under scrutiny for Australia’s life insurance sector. The watchdog reported 10,697 Code breaches affecting 27,289 customers, sanctioned two unnamed insurers for serious non-compliance and confirmed that a dedicated claims-handling inquiry will remain a priority in 2026–27. - read more
New industry claims reporting from Australia’s life insurance sector has reinforced an important point for employers: life cover is not an abstract employee benefit. It is a financial safety net that is tested every year by death, disability, serious illness and extended time away from work. - read more
Fresh life insurance performance data from APRA points to a market that is steadier than the disrupted conditions seen in recent years, but not one where employers can afford to be passive. For CFOs, HR leaders and directors, the message is less about a single quarterly result and more about the operating environment behind corporate life insurance pricing, claims service and product design. - read more
Corporate life insurance in Australia can refer to several different arrangements, including group employee cover, key person insurance, company-owned policies and voluntary employee-paid options. Understanding who owns the policy, who is insured and who receives the benefit is essential before comparing cover. - read more
For many business owners, insurance may seem like a complex and daunting topic. However, understanding the basics of business insurance is crucial in safeguarding your enterprise against unforeseen risks. Business insurance serves as a safety net, providing coverage for various potential incidents that could impact your company's financial health and stability. - read more
Corporate insurance might not be the first thing on your mind when running a business, yet it plays a crucial role in safeguarding your enterprise. Whether you're a small local shop or a bustling company, having the right insurance ensures that your business can withstand the unexpected. - read more
Group life insurance can help Australian businesses provide employee life cover under one policy, but eligibility, underwriting and administration rules matter. This guide explains how employee categories, automatic acceptance limits, waiting periods, claims and annual reviews usually work. - read more
Knowledgebase
Insurance Deductible: That part of an insurance claim that must be paid by an insured person before the the balance is paid by the insurer.
 This week: a claims review finds insurers communication gaps on longer TPD and income protection cases, prompting fixes; ASIC begins another audit of adviser qualifications and warns licensees to keep the register accurate; life-insurtech LifeBid shifts to commercial rollout with major insurer integrations to speed policy servicing; and the Financial Services Minister backs a cautious path to price transparency, noting lessons from life insurances genetic testing limits. Takeaways for HR and CFOs: reinforce claims service expectations with insurers, verify your advisers status, ask providers about digital servicing and data security, and document risk‑reduction efforts to explain benefits costs clearly to staff.